 Stock Trading
Now trade in ₹9 Per Order or ₹ 999 Per Month Plans.
 Future & Options
Access F&O contracts with advanced tools for hedging and speculation.
 Currency Trading
Trade in major currency pairs and manage forex exposure efficiently.
 Commodity Trading
Diversify Trading with MCX & NCDEX by Trading in Gold, Silver, Base Metals, Energy, and Agri Products.
 Margin Trading Funding
Boost your buying power with upto 5X, Buy now Pay Later
 Algo Trading
Back test, Paper Trade your logic & Automate your strategies with low-latency APIs.
 Trading View
Leverage Trading View charts and indicators integrated into your trading platform.
 Advanced Options Trading
Execute multi-leg option strategies with precision and insights.
 Stock Lending & Borrowing
Earn passive income by lending stocks securely through SLB.
 Foreign Portfolio Investment
Enable NRIs and FPIs to invest in Indian markets with ease and compliance.
 IPO
Invest in upcoming IPOs online with real-time tracking and instant allotment updates.
 Direct Mutual Funds
0% Commissions by investing in more than +3500 Direct Mutual Fund Scheme.
 Corporate FDRs
Earn fixed returns with low-risk investments in high-rated corporate fixed deposits.
 Stocks SIPs
Build long-term wealth with systematic investment plans in top-performing stocks.
 Bonds & NCDs
Access secure, fixed-income investments through government and corporate bond offerings.
 Depository Services
Safely hold and manage your securities with seamless Demat and DP services with CDSL.
 RMoney Quick
Fast, hassle-free trading in one tap.
 RMoney Rocket
Power-packed platform for active traders.
 Rocket API
Lightning-fast trading API for developers advanced algo traders.
 XTS Algo
Smart algo trading software for precision trades.
 Journey
Tracing our growth and milestones over time.
 Mission & Vision
Guided by purpose, driven by long-term vision.
 Why RMoney Platform
Smart, reliable platform for all investors' needs.
 Management
Experienced leadership driving strategic financial excellence.
 Credentials
Certified expertise with trusted industry recognition.
 Press Release
Latest company news, updates, and announcements.
 Testimonials
Real client stories sharing their success journeys.
 7 Reasons to Invest
Top benefits that make investing with us smart.
 SEBI Registered Research
Trusted insights backed by SEBI-compliant research.
 Our Technology
Advanced tools enabling efficient online trading.
 Blog
Stay updated with expert insights, market trends, and trading strategies through our informative blogs.
 Video
Learn visually with easy-to-understand videos covering trading concepts, tips, and market analysis.
 Podcast
Tune in to insightful discussions and expert opinions anytime, anywhere.
 Telegram Community
Be part of an active trader community sharing ideas, updates, and market opportunities in real-time.
 WhatsApp Updates
Get instant alerts, key market updates, and important notifications directly on WhatsApp.
 Financial Calculators
Plan your trades, margins, and returns efficiently with our smart calculation tools.
 Marketplace
Discover curated tools, strategies, and services designed to enhance your trading experience.
 Daily Research Reports
Stay ahead with timely market insights, trends, and actionable analysis delivered every day.
 Dedicated Advisory
Get personalized guidance and expert recommendations tailored to your trading goals.
 Research Team
Backed by experienced analysts delivering data-driven insights and market expertise.
 Research Reports
Access in-depth reports covering stocks, commodities, and market movements to support informed decisions.
 Feedback
Share your suggestions or concerns to help us improve your experience.
 Downloads
Access important forms, software, and documents in one place.
 Locate Us
Find the nearest RMoney branch or service center quickly.
 Escalation Matrix
Resolve issues faster with our structured support escalation process.
 Back Office
Log in to view trade reports, ledger, and portfolio statements anytime.
 Account Modification
Update personal or bank details linked to your trading account.
 Fund Transfer
Transfer funds instantly online with quick limit updation to your trading account.
 Bank Details
View our registered bank account details for seamless transactions by NEFT, RTGS or IMPS.
 RMoney Rocket Web Version
Experience powerful web-based trading with advanced tools for algo traders.
 Refer & Earn
Invite friends and earn rewards every time they trade with us.


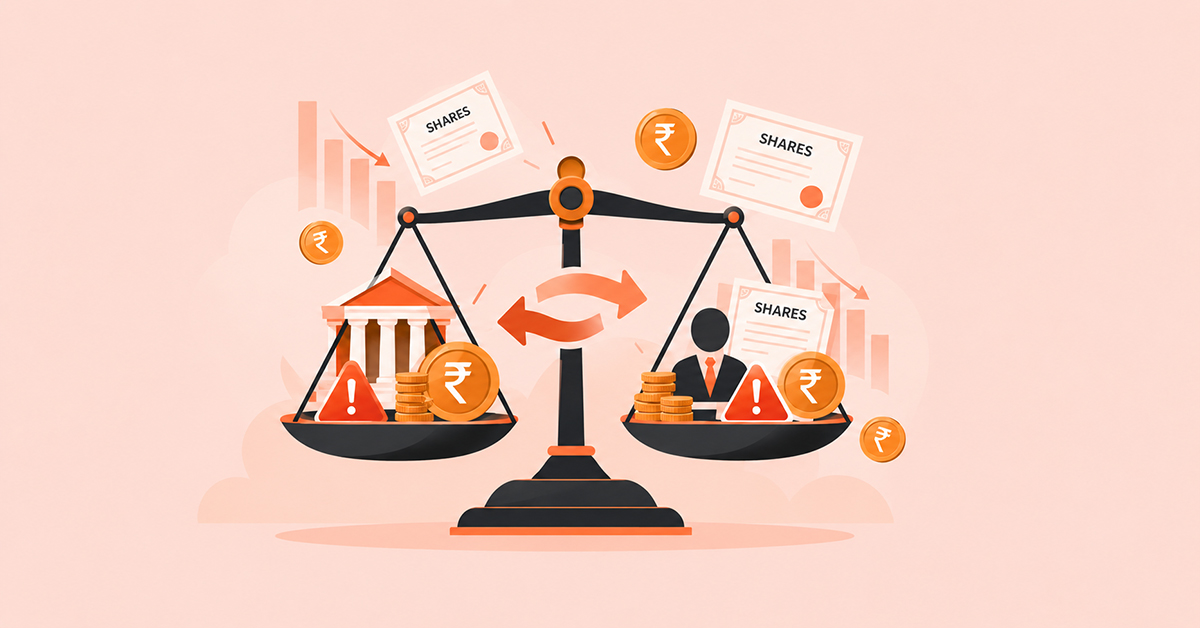
What is SLBM Risk: Risks for Lenders and Borrowers
By: Social | Date : Oct 8, 26
SLBM Risks for Lenders and Borrowers: What You Must Know
SLBM can make trading easier and cheaper, but only if you understand its risks. If you are lending or borrowing shares, you must know these basics.
The Securities Lending and Borrowing Mechanism (SLBM) is a system where investors can lend idle shares or borrow shares for a set period. Lenders earn a fee. Borrowers use it for short selling, arbitrage, or meeting delivery obligations. Both sides face risks. Here is what you need to know.
Is SLBM Safe?
SLBM operates through an exchange and clearing framework with defined margin, settlement and default-handling mechanisms. However, these mechanisms do not eliminate all risks. Lenders and borrowers can still face financial, market, liquidity and operational risks.
SLBM Risks for Lenders
1. High Transaction Costs
SLBM transactions may involve the lending fee along with applicable brokerage, GST, and depository/DP charges. At RMoney, brokerage of 10% + GST is currently levied on the lending fee. Charges may be subject to change, so check the latest applicable SLBM charges before entering a transaction. These charges are separate and may vary based on the transaction. Before lending securities, check the latest SLBM charges and terms applicable to your transaction.
2. Poor Returns for Small Investors
If your demat holdings are modest, For smaller quantities, fixed charges can represent a larger share of the lending income and reduce the net return. Fixed costs dilute across smaller share counts.
3. Early Recall May Involve Timing and Cost Considerations
Lenders have the right to recall early, however, just because the securities are recalled does not mean they will be returned right away. The recall is a transaction for the remaining term, and the charge for lending during that term is determined by the market. Thus, lenders should take into account the process and timing before thinking of early recall.
4. Opportunity Cost
While securities are lent, the lender may not have the same voting rights as when holding the shares directly. Corporate benefits such as dividends and stock splits are handled through the SLB settlement framework, while certain corporate actions can result in foreclosure or adjustment of the contract.
5. Low Liquidity
SLBM demand varies across securities. A lender may not find a matching borrower at the fee or quantity they prefer. You may not find a borrower even if you want to lend.
SLBM Risks for Borrowers
1. Market Risk
If the stock price rises instead of falls, you lose money buying shares back at a higher cost. Even small movements can wipe out profits.
2. Quantity Payback
In case the borrower does not return the securities by the reverse-leg settlement date, NSE Clearing has the option of conducting a buy-in auction. When the securities cannot be acquired by means of the auction, it may take place through the financial closure of the transaction using the closure calculation in use then.
3. Lending Fees
Lending rates will differ depending on the security in question, demand and market conditions. As far as very low availability stocks are concerned, those rates may become extremely high.
4. Collateral Requirements
SLBM transactions will be subject to the relevant requirements for margin and collateral depending on whether the participant is a lender or borrower and at which phase of the transaction they are. As far as the borrower is concerned, they will be subject to margin and collateral requirements under the framework of SLB. This may include lending price collateral, VaR margin, MTM, and other applicable margins. Margins will vary by securities and position.
What Is an SLBM Risk Example?
You borrow 1,000 shares at ₹100 per share and sell them with the anticipation of the price dropping. Unfortunately, the stock price rises to ₹120 instead. To buy back the 1,000 shares that you have sold, you are required to pay ₹120,000, which is much greater than what you received from the original 1,000 shares sold (₹100,000), thus resulting in a loss of ₹20,000, not including other charges or fees applicable in this trading transaction.
Is There an SLBM Risk Calculator?
There is no standard NSE/SEBI calculator specifically called an “SLBM risk calculator.” However, you can estimate potential costs and returns using the lending fee, applicable charges, price movement, and collateral requirements. You can assess risk using:
| Factor | Formula |
| Net Lending Return | Gross fee − Brokerage − GST − DP charges |
| Breakeven Volume | Fixed costs ÷ (Fee per share − Variable costs) |
| Borrower Cost | Lending fee + Collateral opportunity cost + Price movement |
A simple spreadsheet works as your SLBM risk calculator.
Managing These Risks
For Lenders: Make the Costs Worthwhile
In the case of SLBM, it’s more effective if the earnings suffice to cover the cost involved in making the transaction.
- Use this method to lend larger volumes as much as possible.
- Opt for stocks that attract attention in the SLBM market
- Review the NSE SLBM panel prior to lending the shares
- Keep the upcoming AGMs in mind as far as voting power is concerned
For Borrowers: Treat It Like a Trade
Short selling entails market and settlement risks as well.
- Have a stop loss in place beforehand
- Satisfy collateral requirements related to the margin
- Follow the contract and returns as well
- Accept lending fees prior to borrowing
- Observe the stock movements during the whole process
For Both: Know the Terms
Before entering an SLBM transaction, understand the contract and applicable requirements.
- Check the tenure and settlement terms
- Understand the conditions for recall or early return
- Know what happens if shares are not returned on time
- Stay aware of corporate actions such as dividends, bonuses and stock splits
- Contact your broker if you have questions about charges, delays or contract terms.
Using the securities lending and borrowing mechanism (SLBM) has the potential for generating extra income out of irrelevant shares, as well as for being able to borrow shares for purposes of short-selling. Nevertheless, there are costs and risks that must be considered.
From a lender’s point of view, transaction costs, low demand, and opportunity costs can diminish returns. As for the borrower, that trade can turn unprofitable due to rising prices, borrowing fees, collateral requirements, and repayment obligations.
The main rule is to know all costs, evaluate risks, and plan position beforehand. Having fully considered all possible risks, investors can effectively incorporate SLBM into their trading or investment strategies.
Frequently Asked Questions
Q: What is SLBM risk in the stock market?
The SLBM risk is the risk associated with borrowing and lending stock. The lender earns nothing as costs are high, and the borrower suffers from market risk, which is a result of a stock price ascending instead of descending.
Q: What is SLBM risk for lenders?
The main SLBM risk for lenders is low net returns. Brokerage, GST, and fixed DP charges eat into earnings, especially for small quantities. Other risks include loss of voting rights and low borrower demand for most stocks.
Q: What is SLBM risk in stocks?
SLBM risk in stocks is rooted in the type of stocks. Low-volatility stocks of course, bring more market risk for borrowers, whereas low-demand stocks bring liquidity risk for lenders. Only stocks that can be traded in Futures & Options markets can be involved in the SLBM process.
Q: What is an SLBM risk example?
Suppose you borrowed one thousand stocks valued at ₹100, expecting the price to decline. But it actually increased to ₹120, meaning that you will buy back shares at ₹120 and lose ₹20,000 on this deal, which means that your total loss is over ₹21,000 considering fees.
Q: What is an SLBM risk calculator?
There is no official calculator for SLBM risks; however, you can create a simple spreadsheet to calculate net returns (calculated as gross fees minus brokerage, GST, and DP charges) or costs of borrowing (calculated as lending fees and opportunity cost from collateral).
Disclaimer: This blog is for educational purposes only. SLBM involves market risks. Please read all scheme-related documents carefully before investing.
Table of content
Categories
Open Demat Account 
Related Posts
-
Sector rotation – Some important lessons for stock market investors
All sectors do not perform well at the same time. So is the stocks within....
-
All You Need To Know About Debentures
A debenture is a debt instrument that is used by corporations to borrow money for...
-
An Introduction to Exchange Traded Funds (ETFs)
Exchange Traded Funds, popularly called as ETFs, have started gaining popularity among investors. ETFs are...
-
Sensex and Nifty Difference: Understanding Stock Market Index in India
What does it actually mean when the news reports that “Markets are up today”? Is...


Filing Complaints on SCORES (SEBI) – Easy & Quick
- Register on SCORES Portal (SEBI)
- Mandatory details for filing complaints on SCORES:
- Name, PAN, Address, Mobile Number, E-mail ID
- Benefits:
- Effective Communication
- Speedy redressal of the grieva`nces
IT'S TIME TO HAVE SOME FUN!
Your family deserves this time more than we do.
Share happiness with your family today & come back soon. We will be right here.
Investment to ek bahana hai,
humein to khushiyon ko badhana hai.
E-mail
askus@rmoneyindia.com
Customer Care
+91-9568654321
Trade Endlessly with
RMoney
Deep Discount Brokerage Plan
At 999/Monthly
- Dedicated round the clock Advisory Support
- High performance in depth research
- Save more than ₹10,000 brokerage Per Month
- Ultra fast trading app