 Stock Trading
Now trade in ₹9 Per Order or ₹ 999 Per Month Plans.
 Future & Options
Access F&O contracts with advanced tools for hedging and speculation.
 Currency Trading
Trade in major currency pairs and manage forex exposure efficiently.
 Commodity Trading
Diversify Trading with MCX & NCDEX by Trading in Gold, Silver, Base Metals, Energy, and Agri Products.
 Margin Trading Funding
Boost your buying power with upto 5X, Buy now Pay Later
 Algo Trading
Back test, Paper Trade your logic & Automate your strategies with low-latency APIs.
 Trading View
Leverage Trading View charts and indicators integrated into your trading platform.
 Advanced Options Trading
Execute multi-leg option strategies with precision and insights.
 Stock Lending & Borrowing
Earn passive income by lending stocks securely through SLB.
 Foreign Portfolio Investment
Enable NRIs and FPIs to invest in Indian markets with ease and compliance.
 IPO
Invest in upcoming IPOs online with real-time tracking and instant allotment updates.
 Direct Mutual Funds
0% Commissions by investing in more than +3500 Direct Mutual Fund Scheme.
 Corporate FDRs
Earn fixed returns with low-risk investments in high-rated corporate fixed deposits.
 Stocks SIPs
Build long-term wealth with systematic investment plans in top-performing stocks.
 Bonds & NCDs
Access secure, fixed-income investments through government and corporate bond offerings.
 Depository Services
Safely hold and manage your securities with seamless Demat and DP services with CDSL.
 RMoney Quick
Fast, hassle-free trading in one tap.
 RMoney Rocket
Power-packed platform for active traders.
 Rocket API
Lightning-fast trading API for developers advanced algo traders.
 XTS Algo
Smart algo trading software for precision trades.
 Journey
Tracing our growth and milestones over time.
 Mission & Vision
Guided by purpose, driven by long-term vision.
 Why RMoney Platform
Smart, reliable platform for all investors' needs.
 Management
Experienced leadership driving strategic financial excellence.
 Credentials
Certified expertise with trusted industry recognition.
 Press Release
Latest company news, updates, and announcements.
 Testimonials
Real client stories sharing their success journeys.
 7 Reasons to Invest
Top benefits that make investing with us smart.
 SEBI Registered Research
Trusted insights backed by SEBI-compliant research.
 Our Technology
Advanced tools enabling efficient online trading.
 Blog
Stay updated with expert insights, market trends, and trading strategies through our informative blogs.
 Video
Learn visually with easy-to-understand videos covering trading concepts, tips, and market analysis.
 Podcast
Tune in to insightful discussions and expert opinions anytime, anywhere.
 Telegram Community
Be part of an active trader community sharing ideas, updates, and market opportunities in real-time.
 WhatsApp Updates
Get instant alerts, key market updates, and important notifications directly on WhatsApp.
 Financial Calculators
Plan your trades, margins, and returns efficiently with our smart calculation tools.
 Marketplace
Discover curated tools, strategies, and services designed to enhance your trading experience.
 Daily Research Reports
Stay ahead with timely market insights, trends, and actionable analysis delivered every day.
 Dedicated Advisory
Get personalized guidance and expert recommendations tailored to your trading goals.
 Research Team
Backed by experienced analysts delivering data-driven insights and market expertise.
 Research Reports
Access in-depth reports covering stocks, commodities, and market movements to support informed decisions.
 Feedback
Share your suggestions or concerns to help us improve your experience.
 Downloads
Access important forms, software, and documents in one place.
 Locate Us
Find the nearest RMoney branch or service center quickly.
 Escalation Matrix
Resolve issues faster with our structured support escalation process.
 Back Office
Log in to view trade reports, ledger, and portfolio statements anytime.
 Account Modification
Update personal or bank details linked to your trading account.
 Fund Transfer
Transfer funds instantly online with quick limit updation to your trading account.
 Bank Details
View our registered bank account details for seamless transactions by NEFT, RTGS or IMPS.
 RMoney Rocket Web Version
Experience powerful web-based trading with advanced tools for algo traders.
 Refer & Earn
Invite friends and earn rewards every time they trade with us.


EQUITY RESEARCH (26th Sep 2026)
By: Moumita Samanta | Date : Sep 28, 26
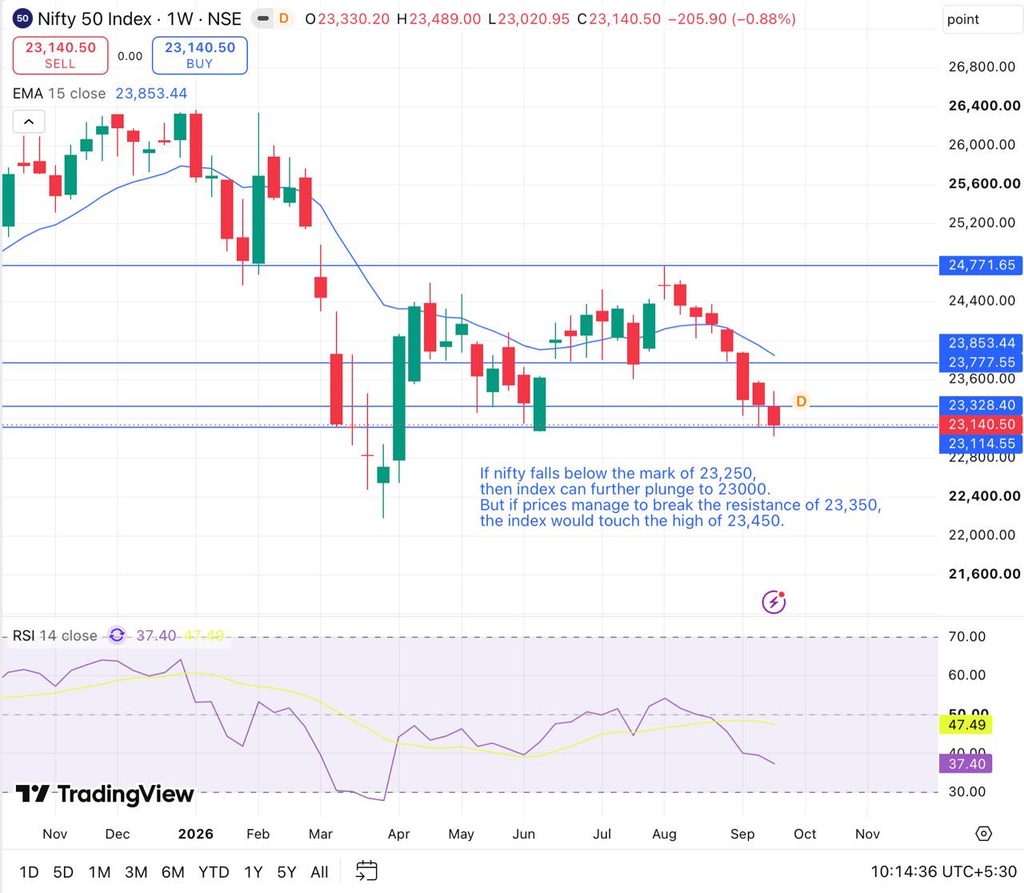
Nifty extended for the eighth consecutive trading week, with no signs of recovery, it continued to bleed. The benchmark index has fallen below the mark 23,250 and closed the session at 23,140.50 with a weekly loss of 0.88%. Amid rising crude oil prices which continued to hover over the mark of $95, along with rising global bond yield and concern over rising US inflation driven by energy prices. Further expectation of another rate hike of 25 bps by FED in October, also weighed on the index. With no conclusion from the US-Iran war also weighed on the index, amid geopolitical tension. Rising bond yield to multi year high along with dollar index reaching above the mark of 101, make investors cautious, and the index failed to gain momentum. Index failing to rise above 23.150 would continue to make index weaker, with FII’s continuously on the selling side and INR weakening also weighed heavily on the index, thus it may further plunge towards the mark of 23,000, in the absence of any upside momentum above the mark of 23,250.
India’s GDP Expectation
S&P global rating index revised Indian GDP growth of FY27 higher to 7% from earlier projection of 6.6% amid stronger than expected industrial activity, healthy consumption, robust good export and services and higher government investment. Further for the year Fy28 and FY the rating agency estimated growth projection at 7.25% and 7%, respectively.
INR performance and FII
INR traded with sideways momentum and managed to gain momentum but sustain previous highs of 96.100, and settled the week at 95.8020. However, higher crude oil prices kept INR weak before the green bucks. INR has breached the crucial resistance of 95.80 , thus it may further depreciate against USD to the level of ₹96.40, if it sustains above the given levelFor the month of September till, FII’s made net sales of ₹18,530.97 crores. FII continued to withdraw money from Indian market from July 2025, with no single month equity purchase by FII
For the week ahead
Domestically, the index would get a direction, taking cues from the performance of INR along with PMI data and Indian industrial production on 28th September to be released this week. Further investors would take cue from escalating Middle East tension which is keeping oil prices elevated above the mark of $95. A further key economic event with a list of US key economic data, like ADP non farm employment change, Core PCE price index, unemployment claims, non farm payroll would be released giving further cues on US economic health.
NIFTY WEEKLY
Nifty 50 traded with negative momentum, for the eighth consecutive week, and has plunged below its crucial mark of 23,250 and closed the week at 23,140.50, down by -0.88%. RSI has also plunged to the mark of 37, indicating pressure in the index. If Nifty fails to pull itself above the mark of 23,250, thus, the index is expected to remain under pressure for the week and it may further weaken to fall to the mark of 23,000. If it gains momentum and manages to break through and sustains above 23,250, then only the nifty would be able to reach 23,450.
BANK NIFTY WEEKLY
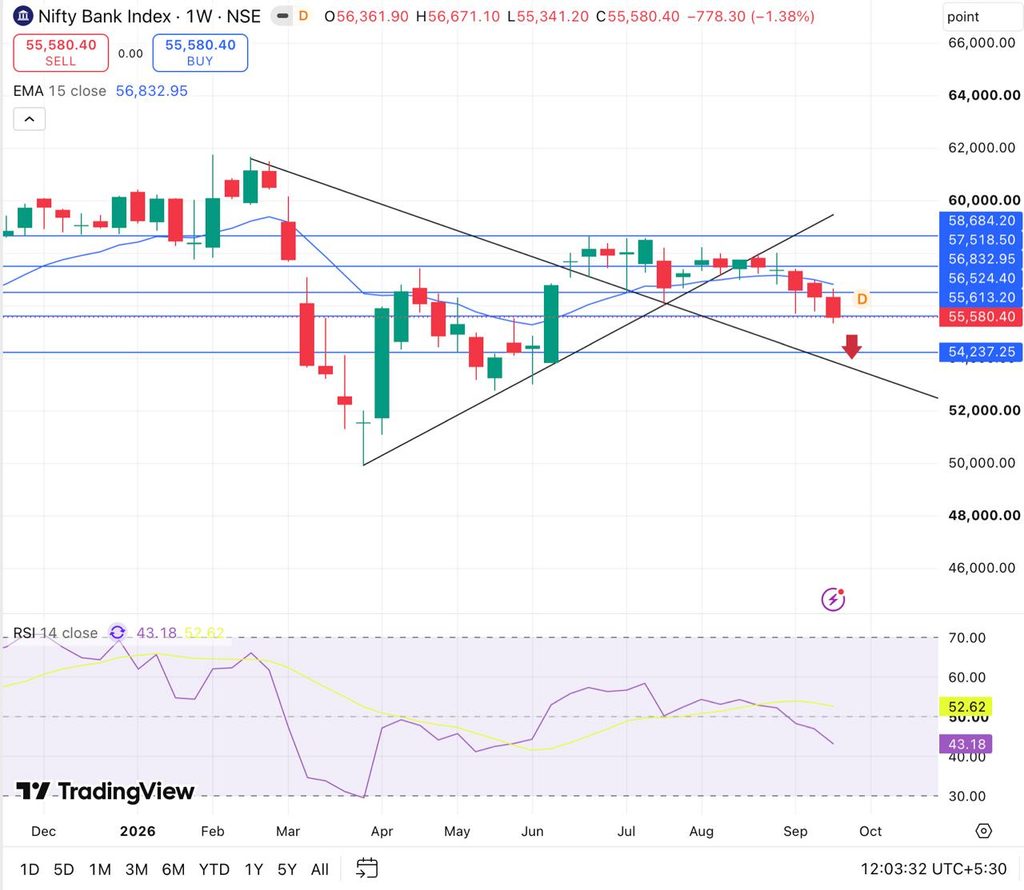
For the fourth consecutive trading week, Bank Nifty traded with negative momentum; the index plunged by 1.38% on a weekly basis, falling to a weekly low of 55,341.20, a crucial level, before settling the week at 55,580.40. Further, the RSI has fallen below the mark of 43 from previous week’s number of 46.98, hinting pressure in the index which may further push the index towards the level of 54,800. Thus for the index to further upside must trade above the level of 55,600 mark to reach the next upside destination of 56,500 level. However, if the index breaks the weekly low of 55,341, then we may see the index slipping to the level of 55870-54,200.
| WEEKLY TECHNICAL DETAILS – NIFTY & BANK NIFTY | ||
| NIFTY | BANK NIFTY | |
| Closing | 23,140 | 55,580.40 |
| Support | 23,000 | 55,300 |
| Resistance | 23450 | 57,100 |
| Weekly Change | -0.88% | -1.38% |
| SECTORAL TREND | ||
| TREND | WEEKLY % CHANGE | |
| Pharma | Upside | 1.01% |
| IT | Down | -2.40% |
| Auto | Down | -0.59% |
| Realty | Sideways | 2.98% |
| FMCG | Upside | 1.04% |
| Energy | Down | -0.88% |
| CURRENCY AND VOLATILITY INDEX | ||
| PREVIOUS CLOSE | % CHANGE | |
| VIX | 12.16 | 6.81% |
| USDINR | 95.8020 | -0.06% |
| Dollar Index | 101.034 | 0.82% |
Disclaimer:
Investment in securities markets is subject to market risks. Please read all related documents carefully before investing. (Our SEBI Reg. No. INH000010335)
For Full Disclaimer: Click Here
Open Demat Account 
Recent Researches
Related Posts
-
EQUITY RESEARCH (19th September 2026)
Nifty extended for the seventh consecutive trading week, continuing to bleed, with no signs of...
-
WEEKLY REPORT
Nifty traded with negative bias for the second straight week and plunged by 181.05 points...
-
EQUITY RESEARCH (25th July 2026)
The Nifty 50 traded with negative bias and lost its ground to touch the weekly...
-
EQUITY RESEARCH (08th Aug 2026)
Nifty extended its gaining streak for the second consecutive trading week and settled with a...


Filing Complaints on SCORES (SEBI) – Easy & Quick
- Register on SCORES Portal (SEBI)
- Mandatory details for filing complaints on SCORES:
- Name, PAN, Address, Mobile Number, E-mail ID
- Benefits:
- Effective Communication
- Speedy redressal of the grieva`nces
IT'S TIME TO HAVE SOME FUN!
Your family deserves this time more than we do.
Share happiness with your family today & come back soon. We will be right here.
Investment to ek bahana hai,
humein to khushiyon ko badhana hai.
E-mail
askus@rmoneyindia.com
Customer Care
+91-9568654321
Trade Endlessly with
RMoney
Deep Discount Brokerage Plan
At 999/Monthly
- Dedicated round the clock Advisory Support
- High performance in depth research
- Save more than ₹10,000 brokerage Per Month
- Ultra fast trading app